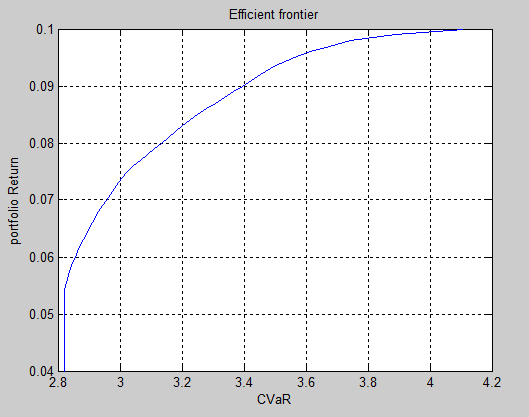
CVaR optimization
The file provides scripts and functions to estimate the optimal portfolio by minimizing CVaR

You are now following this Submission
- You will see updates in your followed content feed
- You may receive emails, depending on your communication preferences
Cite As
Manthos Vogiatzoglou (2026). CVaR optimization (https://ch.mathworks.com/matlabcentral/fileexchange/19907-cvar-optimization), MATLAB Central File Exchange. Retrieved .
Categories
Find more on Portfolio Optimization for Asset Allocation in Help Center and MATLAB Answers
General Information
- Version 1.0.0 (5.33 KB)
MATLAB Release Compatibility
- Compatible with any release
Platform Compatibility
- Windows
- macOS
- Linux
| Version | Published | Release Notes | Action |
|---|---|---|---|
| 1.0.0 | a bug about short position is now fixed |

